It's a spooky edition this week, with lots happening. And trying something new this week: graphs!
Let's start with the Creature of Jekyll Island: The Fed voted 10-2 to keep rates as-is. Warsh made concerns about inflation, and said he wants to see inflation back under 2%.
But Michael, you might ask, why would they cite that concern and then keep rates as-is despite every inflationary metric, including this week's PCE, showing increased inflation? Not at all related to midterms, I assure you (go vote).
Less votes: Warsh also announced fewer meetings for rate hikes in upcoming years. One less next year, and two less in 2028. My strong guess is we'll see October fade like a ghost and convert to purely strategy meeting, so less chance he has to play politics before elections in future years.
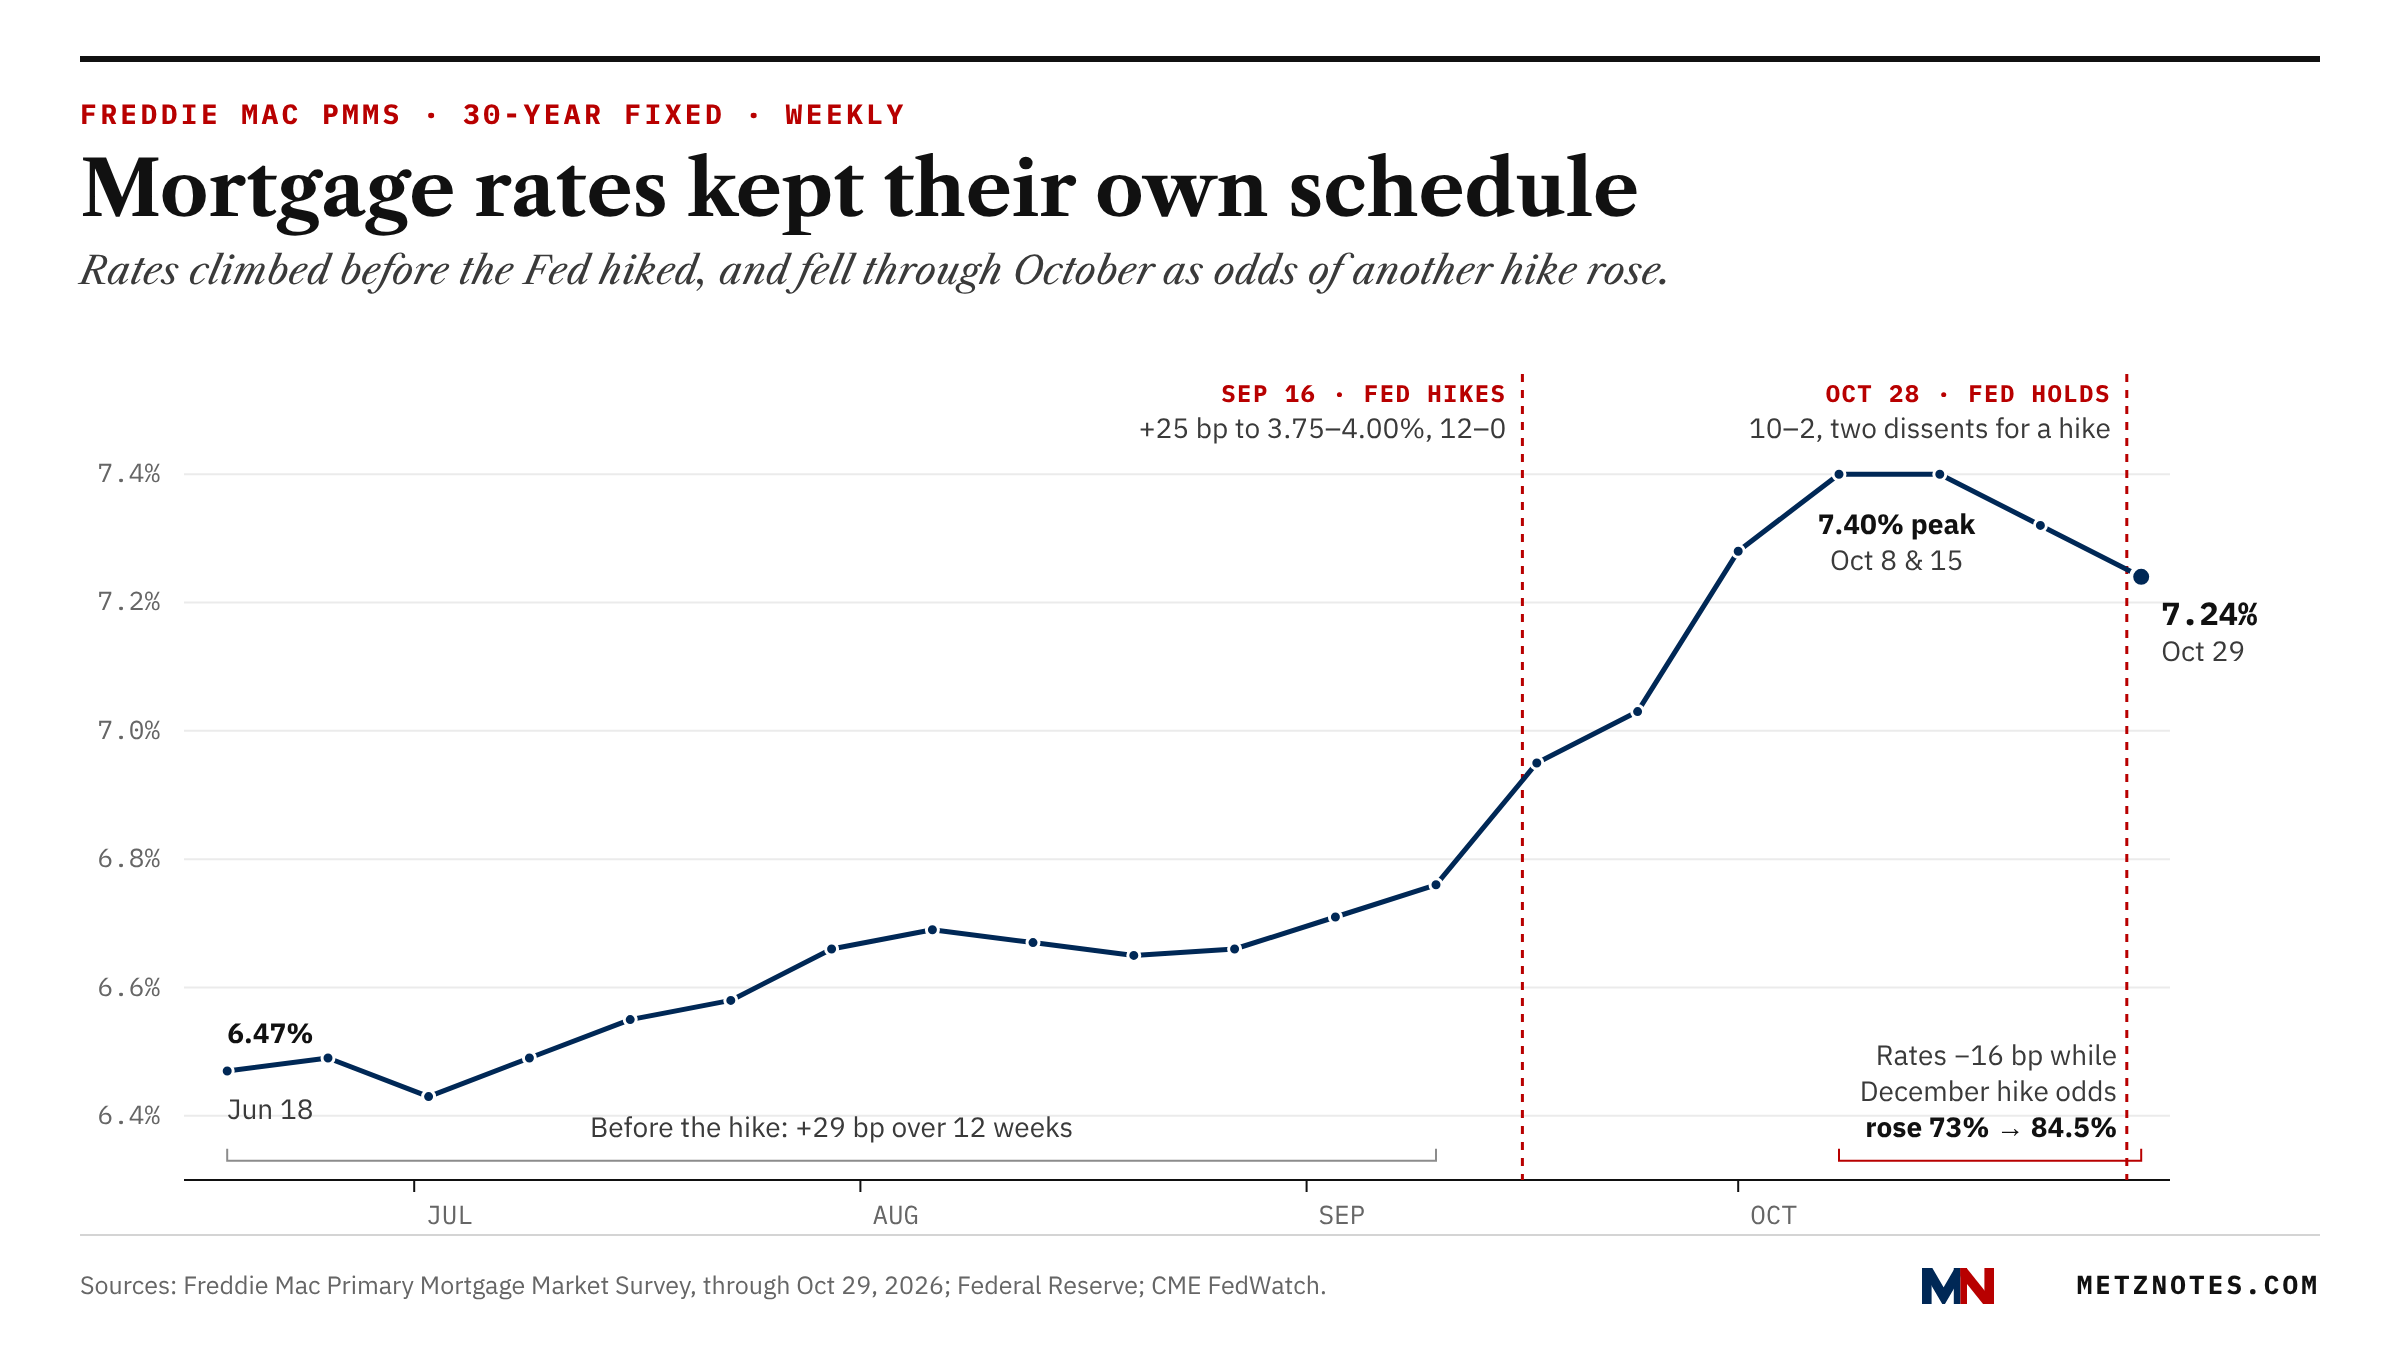
Rates: AI and tech falls (sorry, Alphabet) caused investors to flee to bonds, and so we saw rates drop 8BPS to 7.24%. We're still 107BPS up, but things are looking like they're steadying. Let's try a graph!
Positive News: Lots of positive news this week. Let's run through them quickly.
Appreciation: FHFA's House Price Index showed us annualized at 2.4% and Case-Shiller at 2.1%, better than we've been seeing.
September New Home Sales were only down .6% for the month, far better than the 4.5% anticipated. Consumer Confidence went up a solid 7.5 points, with present situation being the biggest winner. Purchase apps backed that up, and we saw a 4% WoW increase. PCE and GDP followed up, with PCE showing 3.6% inflation (less bad than anticipated) and GDP at 3.4% annualized, up from 2.2% in Q2.
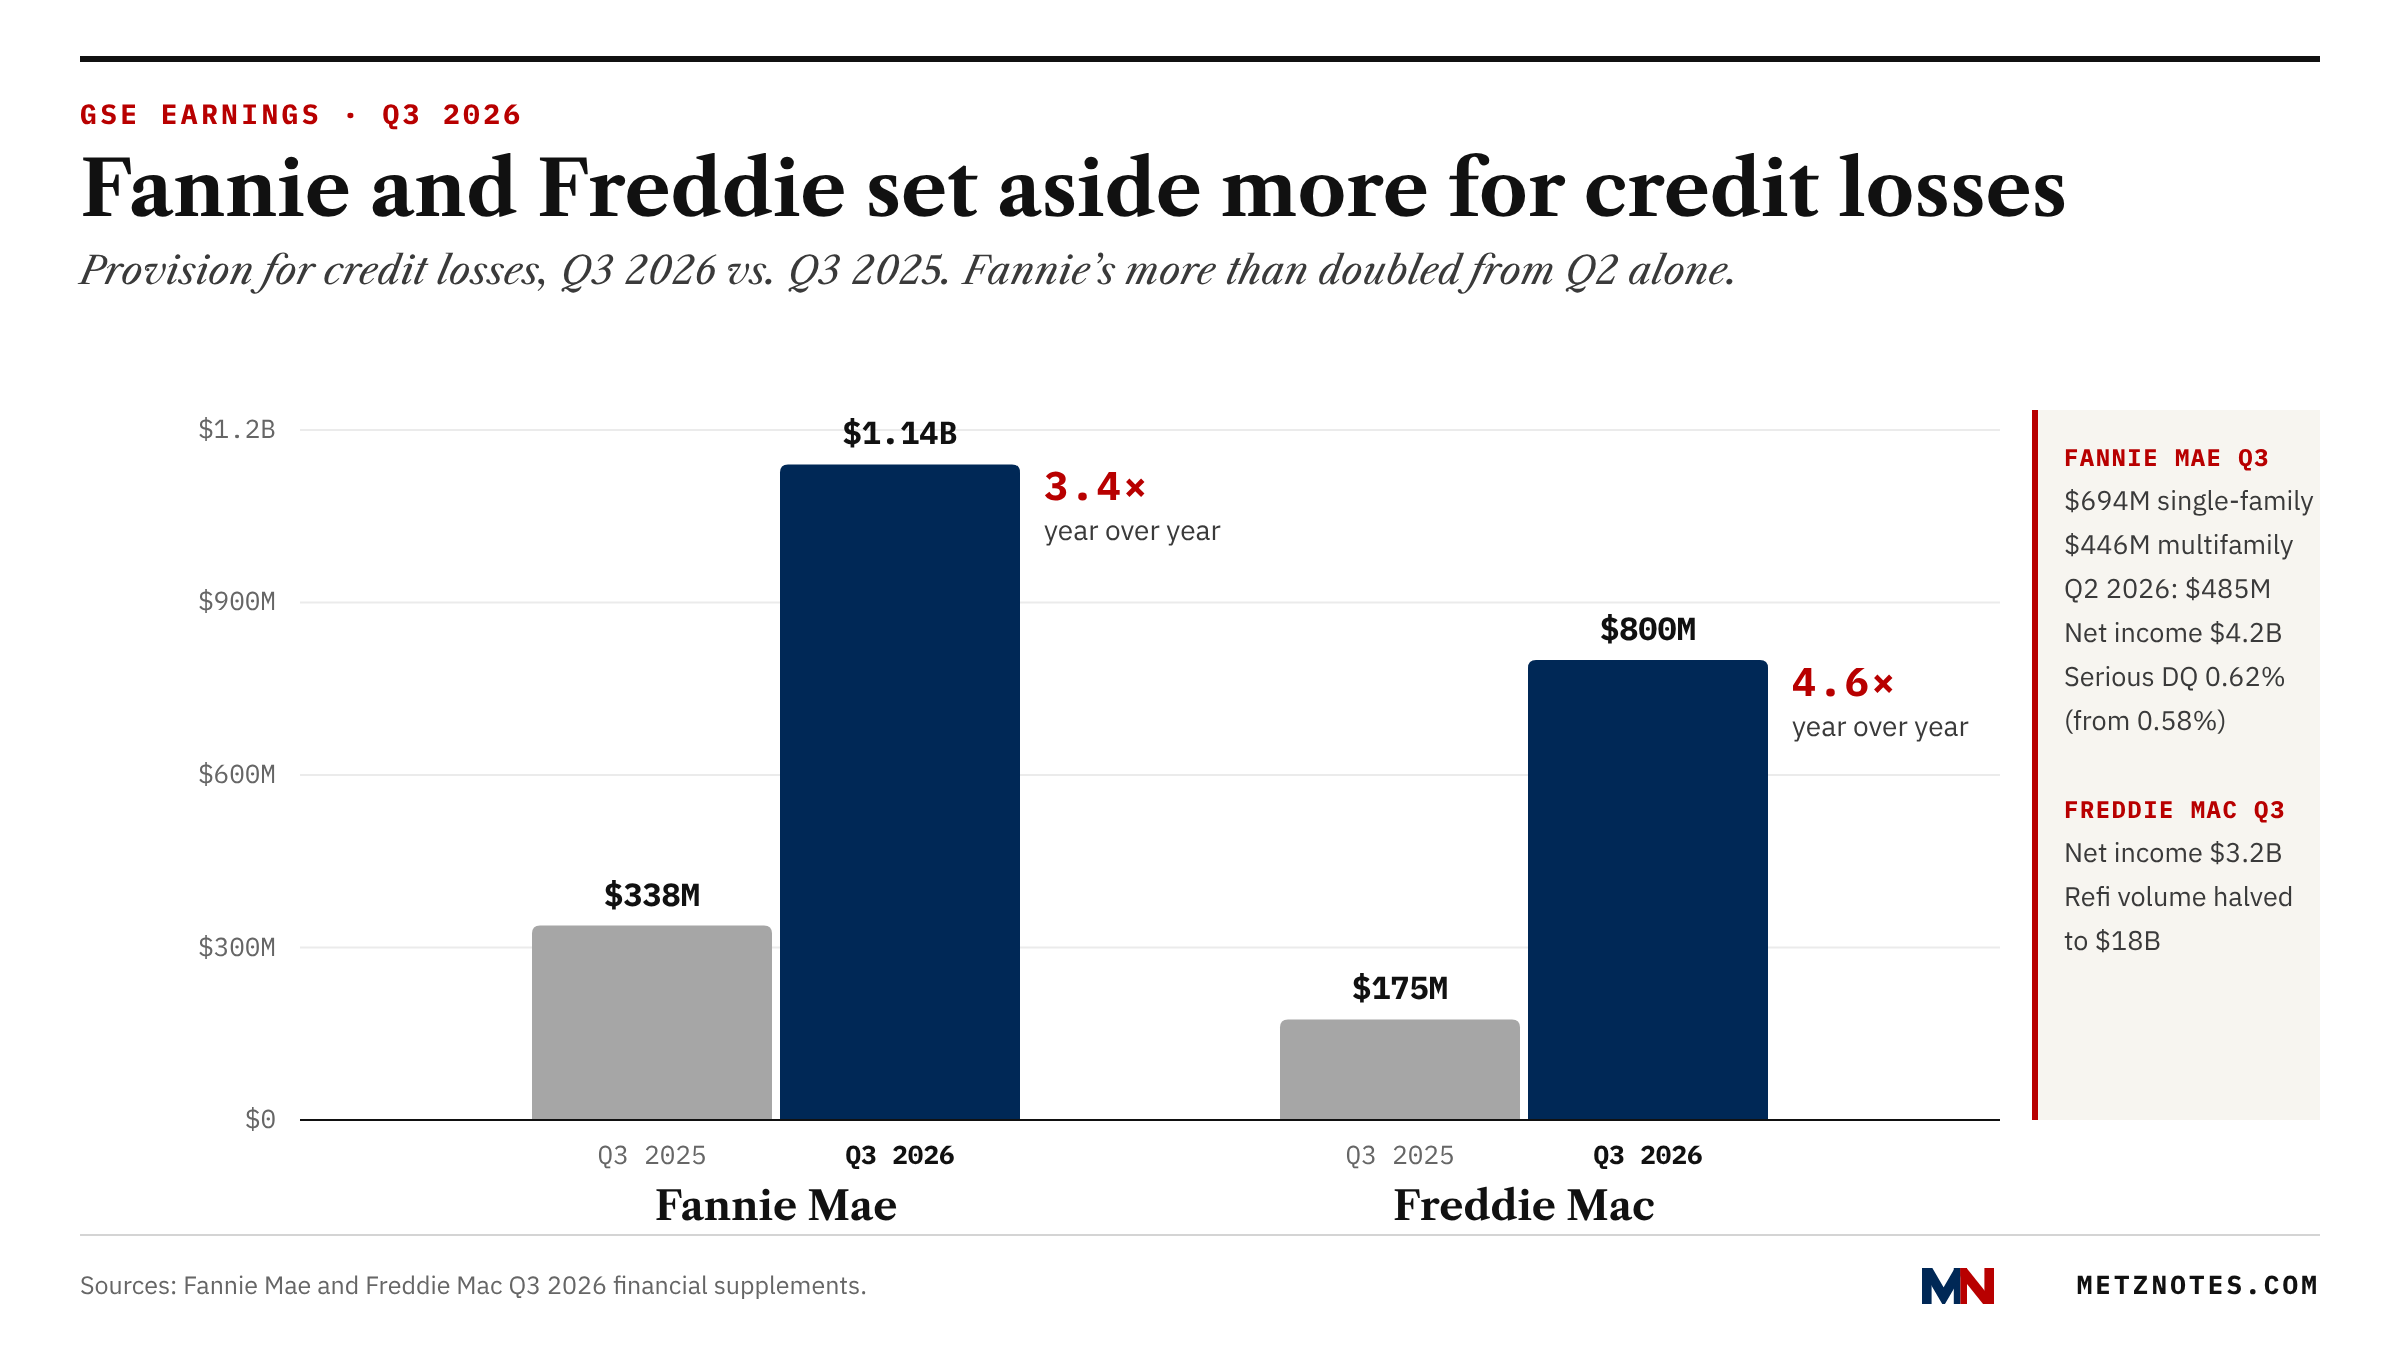
Fannie and Freddie: In a world where lenders are worried about profitability and M&As are through the roof, Fannie pulled in $4.2B last quarter and Freddie $3.2%. Of more interest to me, though, were their increases in reserves. A lot of it is due to multifamily, where MF investors refinanced with higher leverage in yesteryear's lower rates and now can't quite make their debt-ratios work as they refi. Delinquencies are up, and Freddie alone went up to $800M in reserves to prepare for it. How big an increase is it? Let's look at a pretty picture.
Go vote if you haven't already, and enjoy your Halloweekend!