Let's start off with employment, shall we? It was a gangbusters week for 'em.
Short version: Lots of jobbing happening.
JOLTS started us off with job openings coming in at 7.52M versus the expectations at 7.1M. Hires were up 3.4%, quits only at 2.1%, and layoffs were down to 1%.
ADP kept the trend going, with payrolls coming in at 86K versus the expected 67K. We finally saw non-healthcare growth more substantial, with healthcare/education only being +28K of that +86K.
Challenger Job Cuts showed only 2% MoM (43K job cuts), and initial jobless claims only at 189K, less than expected.
NFP's Payrolls was the big news: +165K versus expected +62K, the most in seven months. September and August both revised up by about 40K each month, and unemployment notched down .1% to 4.1%. All positive!
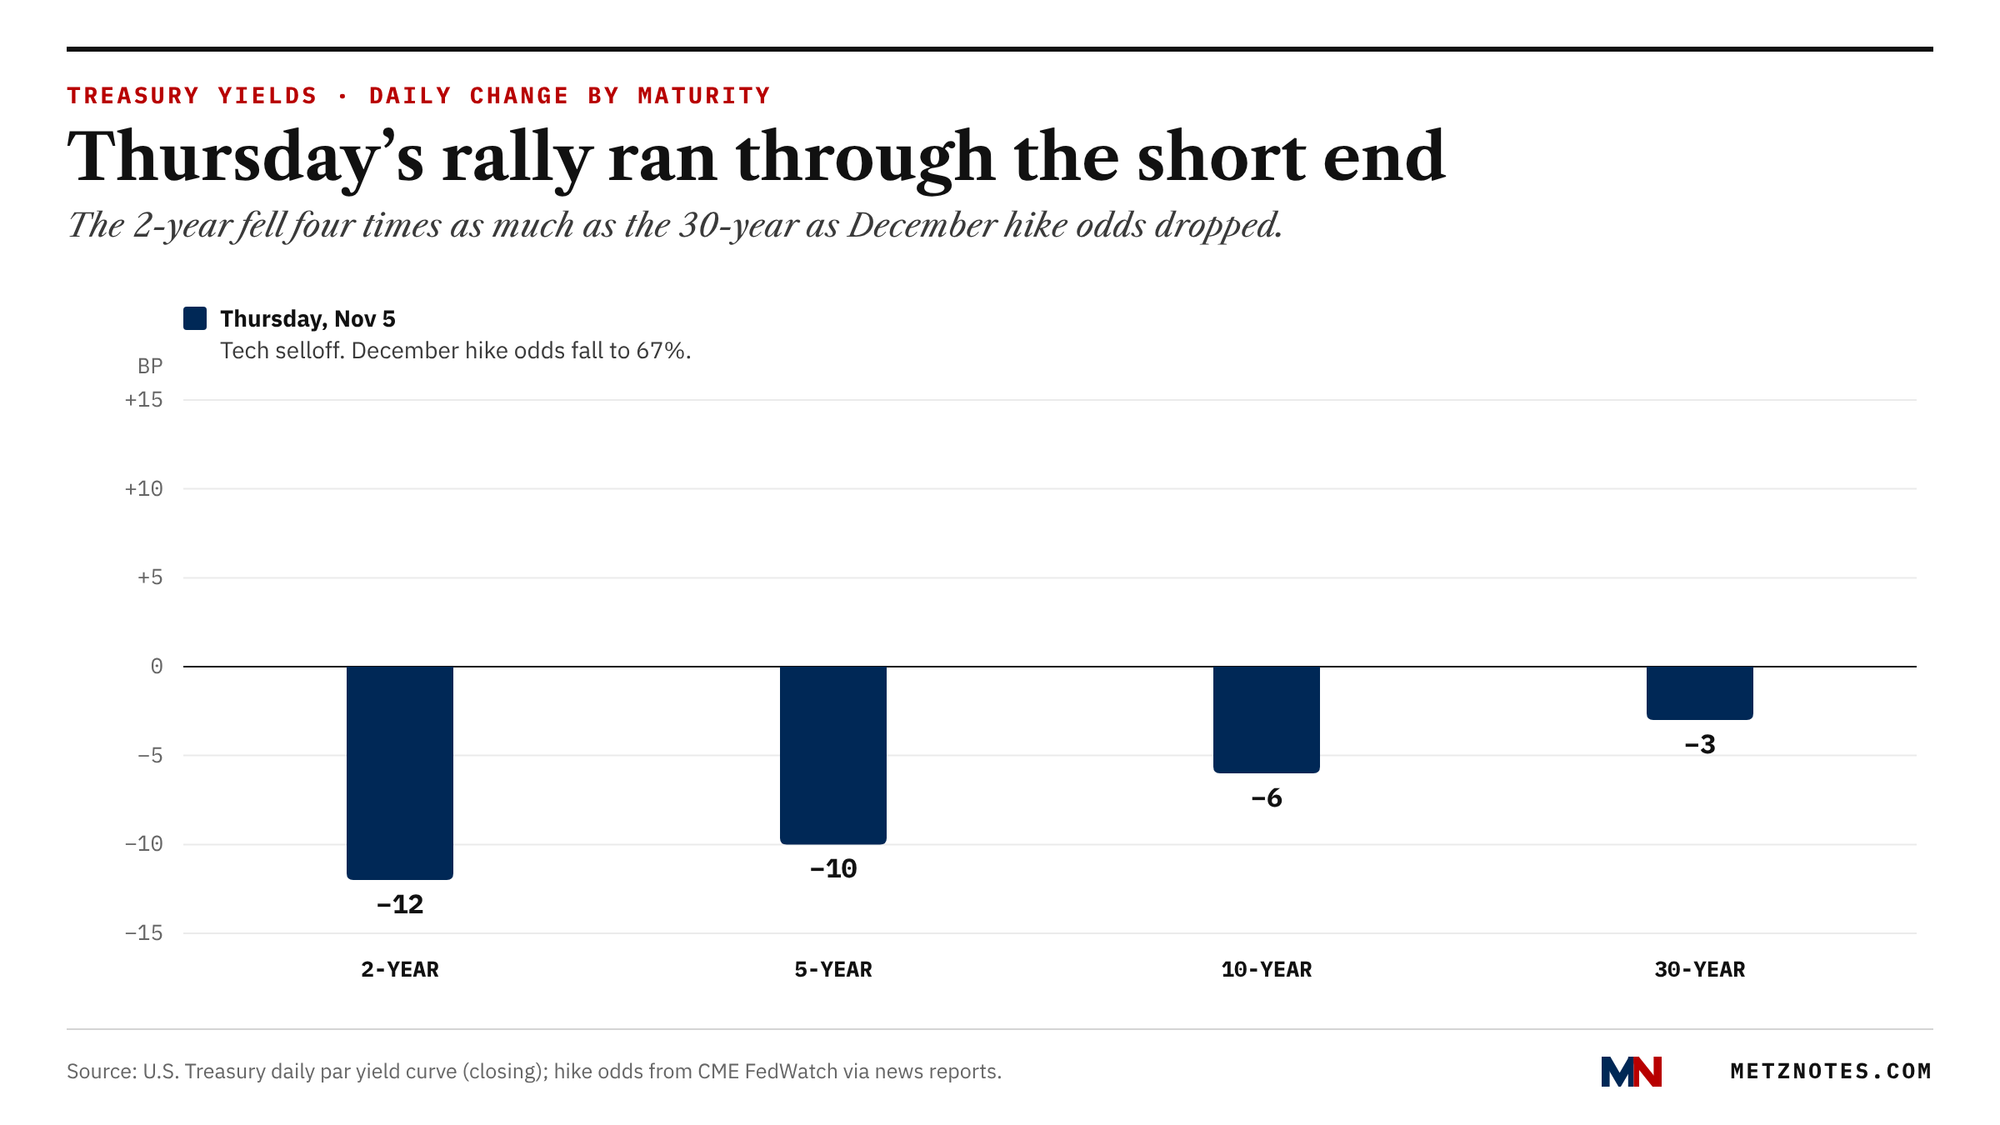
Stocks bounced around both ways post-election which helped bonds. Rates ended up down 6BPS for the week, our third decline. It stopped the bleeding, but apps still stayed stagnant with a 1.2% decrease for the week.
Now, let's talk elections. What's actually likely to matter for us? Let's start off with rates.
1.) Tech & Bonds: Short-term, equities bouncing around has a flight to bonds. Medium-term, there's going to be a shift from heavy AI investments that were depleting MBS purchases (reference prior week posts!). I doubt we'll see it happen at the same rate we have this week, but I think it'll keep moving in the right direction.
2.) Iran & International: There's agreement on both R/D that the Iran situationship needs to resolve. That'd be fantastic for oil, and overall inflation, and bonds/rates. There's also less trade war action likely to be happening which will cause the same.
3.) The Big Players: Fannie and Freddie privatization parties are cancelled. Despite some headlines and posts I'm reading, the CFPB isn't likely to make a zombie act here. A few reasons for that:
Funding: Their funding reduction was passed in legislation, and getting it reverted will not be as easy. That's going to be a likely veto target, and overcoming the veto will be unlikely.
Staffing: Even if they manage the magical funding, bringing staffing back will be a challenge and take time. Most of the people have taken new jobs since then.
Oversight: Changing oversight, and changing leadership, will still be a long, painful slog with lots of drama.
Bigger Fish to Fry: I doubt anyone's going to pick this up as a battle flag. There will be lots bigger issues many are going to care about, and this won't be where they stake their claim. My guess is it's a 2029 play versus now.